By Bec Milligan.
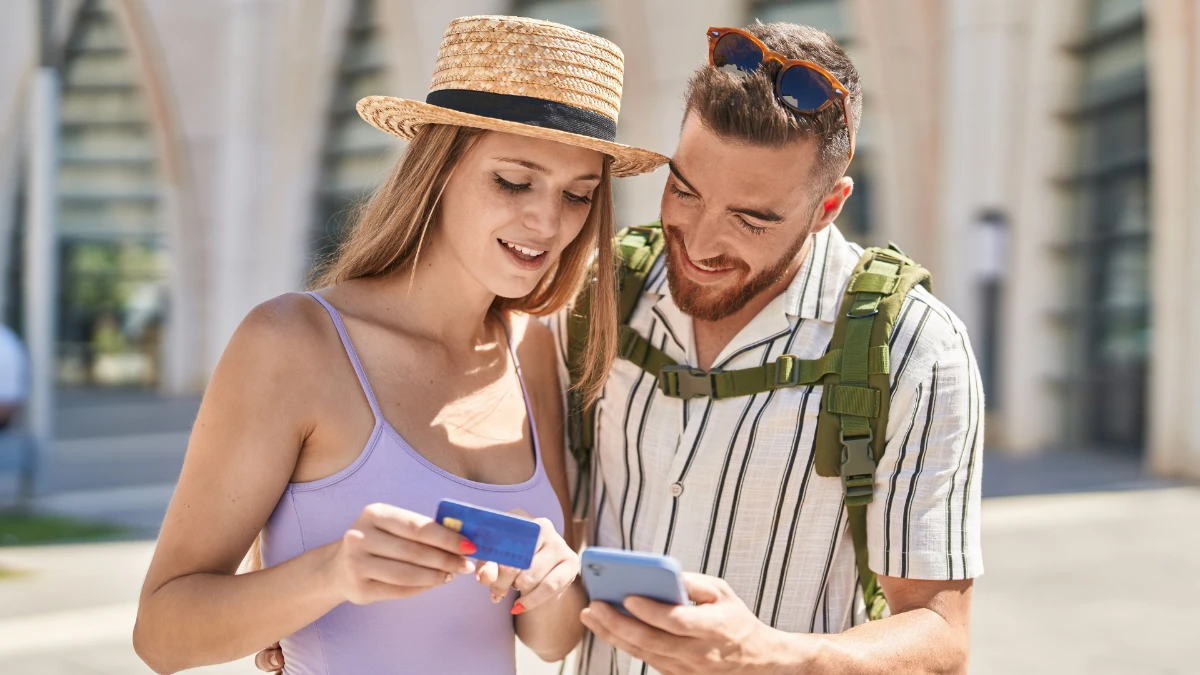
Thousands of Australians travel each year assuming their credit card has them covered. And while many premium cards do include some form of travel insurance, the details matter. A lot.
Activation requirements, exclusions, and coverage gaps mean that credit card travel insurance often isn’t the complete safety net travellers expect. Here’s what you need to know before you go.
Some do but not all, and not automatically. Travel insurance is generally only available on premium or rewards credit cards (think Platinum or Black tier), which typically carry higher annual fees.
If you hold a standard or low-fee card, chances are you have no travel insurance at all.
Even on cards that do include cover, it’s rarely switched on by default. Most major Australian banks require you to activate your cover by spending a minimum amount on prepaid travel costs (think flights, accommodation, and tours) on that card before you depart.
So, if you miss that threshold, book your flights on a different card, or simply forget, you may be travelling completely uninsured without realising it.
Not to mention, credit card travel insurance itself is changing. New rules affecting how banks make money on card payments come into effect in October 2026, and because complimentary perks like travel insurance have traditionally been funded out of that revenue, a number of major banks are quietly scaling theirs back.
Some have already cut benefits or tightened limits and others are set to make changes later this year (see more on this below). Plus, some cards that used to activate automatically once you’d spent enough on travel bookings now require you to log in to your banking app and turn it on yourself.
The bottom line? Check that your card remains eligible, find out exactly what’s included (and excluded), and confirm whether there’s anything you need to do to activate the travel insurance before you head off.
Credit card travel insurance and standalone travel insurance can both provide valuable cover.
However, benefits, limits, eligibility requirements and exclusions vary between providers and
products. Before travelling, it's important to check what cover is available and whether it
suits your needs and circumstances.
| Credit Card Travel Insurance | Standalone Travel Insurance |
|---|---|
|
Eligibility requirements may apply before cover becomes available, such as minimum spend or card usage requirements. |
Can generally be purchased regardless of how travel was booked, subject to policy terms and conditions. |
|
Some policies may require activation or
|
Cover generally starts once the policy is purchased, subject to policy terms and conditions. |
|
Medical cover, limits and exclusions vary between providers and products. |
Medical cover, limits and exclusions vary between insurers and policies. |
|
Cover for pre-existing medical conditions may be limited, excluded or subject to eligibility criteria. |
Cover for some pre-existing medical |
|
Age limits or other eligibility criteria may apply. |
Eligibility requirements and premiums may vary depending on factors such as age, destination and trip type. |
|
Maximum trip durations may apply and vary between providers. |
Policy options may be available for different trip lengths, subject to insurer limits and terms. |
|
Excess amounts vary between providers and products. |
Excess amounts vary between insurers and policies. |
|
Cover for activities such as skiing, cruising or adventure sports varies between providers and products. |
Cover for activities such as skiing, cruising or adventure sports varies between insurers and policies. |
|
Cover for loss or theft of cash varies between providers and products. |
Cover for loss or theft of cash varies between insurers and policies. |
|
Travel insurance benefits may be included with card membership, subject to eligibility requirements and conditions. |
Premiums vary depending on the traveller, destination, trip duration and level of cover selected. |
|
Claims processes and support arrangements vary between providers and insurers. |
Claims processes and support arrangements vary between insurers. |
Credit card travel insurance can provide valuable cover, but benefits, limits, exclusions and
eligibility requirements vary between providers. Before relying on any travel insurance
product, check the Product Disclosure Statement (PDS) and other policy documents to
understand what is and isn't covered, and whether the cover suits your travel plans and
personal circumstances.
No. Travel insurance is generally only available on premium or rewards cards with higher annual fees. If you hold a standard or low-fee card, you likely have no cover at all.
Not usually. Most cards require you to spend a minimum amount on prepaid travel costs using that card before you depart. Some also require online registration. If you miss the threshold, pay with a different card, or forget the step entirely, you may be uninsured without realising it.
Sometimes, but with conditions. A spouse and dependent children may be covered, but they generally need to travel with the primary cardholder for the entire trip, and their travel costs usually need to have been paid on the same card. If you’re travelling with grandchildren, check carefully, as the definition of “dependant” varies between providers.
Many providers don't cover one-way or open-ended trips. If your travel plans don’t include a return booking, check with your card provider before you go.
Often not before you depart. Many credit card policies only activate once your trip has started, meaning if something prevents you from travelling at all, you won’t be able to claim. A standalone 1Cover policy is active from the moment you purchase it.
It can be more complicated than claiming on a standalone policy. With credit card insurance, the provider who sold you the card is rarely the same team handling your claim. With 1Cover, the same team that sells you your policy is the team that supports you if something goes wrong, including 24/7 Emergency Assistance when you’re overseas.
Most credit card travel insurance only covers international trips. Check your card’s PDS if you’re planning a domestic holiday and want to be sure.
No. Policies vary significantly between providers; Commonwealth Bank, Westpac, ANZ, and NAB all have different terms, excesses, and exclusions. Some may exclude cruising, skiing, or pre-existing conditions. Always read the PDS before you travel.
Generally, yes. Banks and airlines typically have commercial arrangements with the insurers they partner with. Commission structures vary, so it’s always worth reading the PDS and comparing your card’s cover against a standalone policy.
Many credit card policies don’t automatically cover pre-existing medical conditions.
Some providers won’t allow you to pay an additional premium to add cover for your condition either, which can leave you with no options at all.
The added complication is that most travellers have never had any direct contact with their card’s insurance provider; they simply activate the cover and assume they’re protected.
If you have a pre-existing condition and plan to rely on your credit card insurance, contact the insurer directly before you travel. Get any agreed coverage confirmed in writing, obtain a doctor’s clearance for travel, and keep all documentation. And remember, even a condition that appears resolved through surgery or medication may still be treated as pre-existing by your insurer.
With a standalone policy like the ones provided by 1Cover, pre-existing conditions are assessed upfront.
Depending on your condition, you may be able to cover it for an additional premium, travel with it excluded, or understand clearly what your options are. Before you leave home, not after something goes wrong.
Many credit card insurers exclude pregnant travellers from cover entirely. Even where some coverage exists, there may be restrictions on claims, higher excesses, or additional premiums.
Standalone travel insurers are generally more accommodating; many can cover pregnant travellers through the second trimester, though restrictions always apply.
Routine antenatal care and childbirth will not be covered under any travel insurance policy. If you’re pregnant and planning to travel, the key is to understand exactly what applies to your specific situation before you book.
If you do decide to go with credit card travel insurance, here are a few tips so you can make the most of it.
Different cards may offer what seems like comprehensive travel insurance on the surface, but it might be a different product altogether. There are three types of insurance you could be offered:
Some providers offer all three; some offer a combination, and some only offer one. Make sure you understand exactly what you’re getting before you travel, especially in light of all the changes coming into effect in 2026.
Some credit card companies require you to activate your cover online before you depart. Others don’t, but you may only be getting basic cover as a result. If you’re unsure, contact your provider directly.
Also take note of the minimum spend required to trigger your cover. If the threshold is $800 and your flights cost $750, you won’t be covered. And check whether a return ticket is required; some providers won’t cover one-way trips.
Even a routine prescription in the past year can affect your policy. If in doubt, discuss it with your provider before you travel, and make sure you have written confirmation that your condition has been declared and noted.
Make copies of your travel documents, drivers licence, tickets, doctors certificates, receipts and valuations for any expensive items, insurance papers, and any additional coverage details. If something does go wrong, obtain a police report or local doctor’s report and keep copies of everything.
This is especially important if you’re travelling to countries like the United States, where a short hospital stay can easily exceed the upper limits of a credit card policy.
If you’re considering applying for a new credit card specifically for its travel insurance, weigh up the full cost of the card:
Confirm whether your planned activities are covered before you go; your provider’s 24/7 assistance line can advise you. Also check the car rental excess provisions carefully, as some policies only cover certain vehicle types such as sedans or station wagons.
 From booking it at the best possible price to getting a few Zs, here's how to have a successful flight.
 Sadly, more than 980 Australians are robbed while on an international trip every year. But here's exactly what to do...


1Cover ® is a registered trademark of 1Cover Pty Ltd. 1Cover Pty Ltd ABN 91 105 954 265, is an authorised representative of Coffre-Fort Pty Limited ABN 66 125 358 518, AFS Licence No. 472457. 1Cover is located at Level 1, 332 Kent Street, Sydney NSW 2000. Before you buy, please read the Product Disclosure Statement and Target Market Determination. Any information contained on this website is general advice only and has been prepared without taking into account your objectives, financial situation or needs. You should consider these having regard to the Product Disclosure Statement (‘PDS’). Before you purchase, please note in particular, the eligibility criteria, travel warnings in place and limitations to claim under multiple policy sections.
This insurance is underwritten by HDI Global Specialty SE, a company registered in Germany acting through its Australian branch, HDI Global Specialty SE – Australia, ABN 58 129 395 544, AFSL 458776.


 AU
 NZ